Credit Scores Demystified: What Matters and How to Improve
Confused by credit scores? Learn what factors matter most, what doesn't, and proven steps to raise your score quickly and sustainably.
Understanding Credit Scores
Your credit score is a three-digit summary of how reliably you manage borrowed money. Lenders, landlords, insurers, and sometimes employers consult it to gauge risk before they offer terms. Think of it as a snapshot of your borrowing behavior, not a judgment of your character or net worth. A high score generally signals lower risk, which can unlock better interest rates, higher limits, and smoother approvals. A lower score suggests higher risk, which can raise costs or require deposits. Scores move because the information in your credit reports changes: payments post, balances update, accounts age, and inquiries appear. Different scoring models exist, but they tend to reward the same core habits: on-time payments, low credit utilization, and responsible account management over time. Remember, a credit score is not a savings account, investment portfolio, or income measure; it is a risk assessment tool. Treat it as feedback that helps you build healthier personal finance decisions and access credit on terms that support your goals.
The Factors That Matter Most
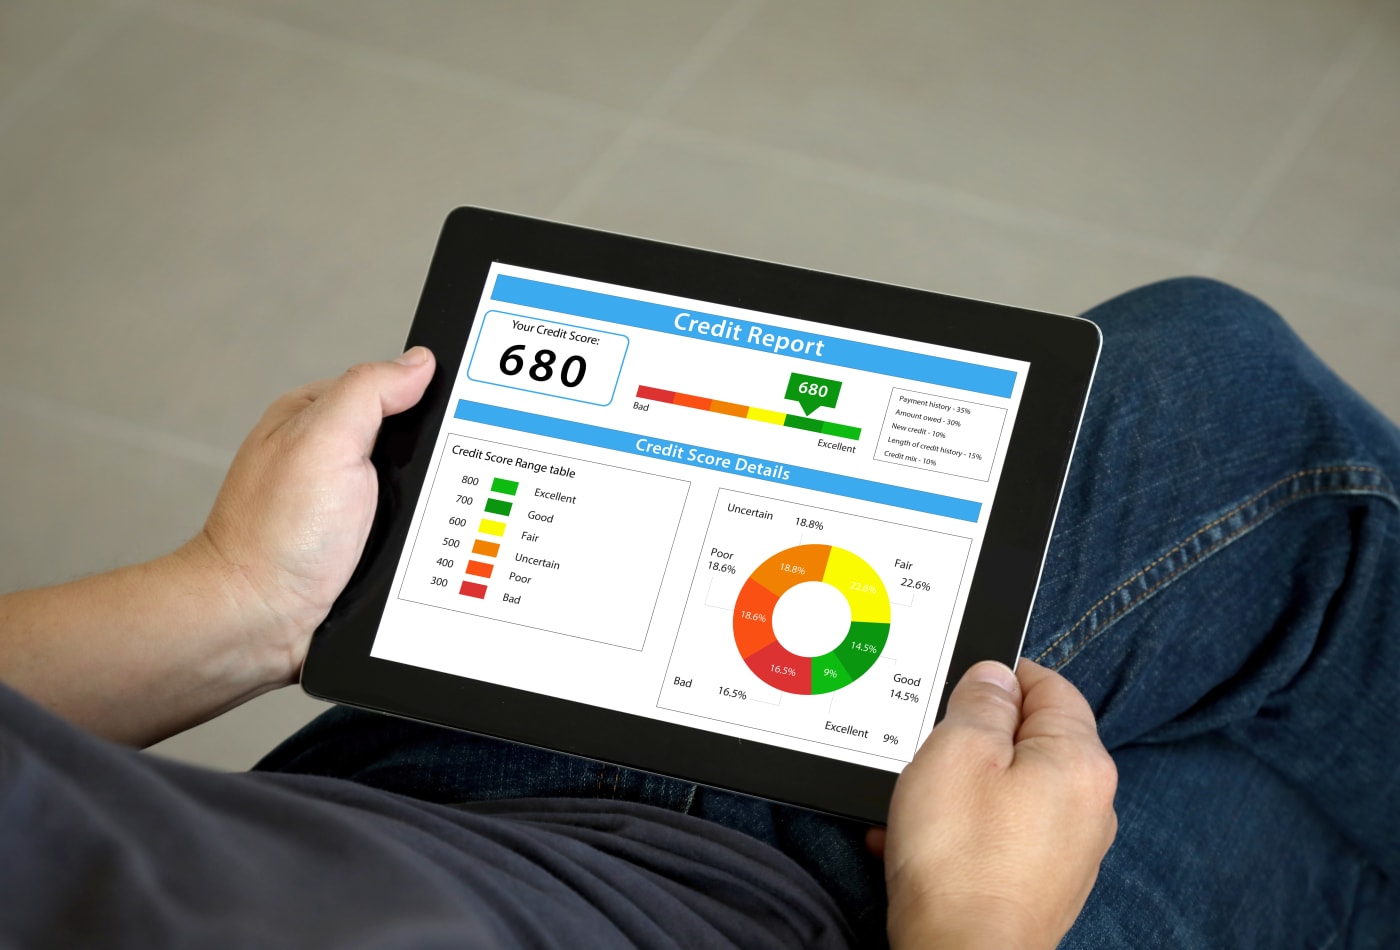
Five core ingredients typically shape your score. First is payment history: consistently paying on time is the single most powerful signal of reliability. Second is credit utilization, the share of revolving limits you are using; lower is generally better because it shows restraint and flexibility. Third is the length of credit history, which reflects how long your accounts have been open and active; older, well-managed accounts add stability. Fourth is new credit, including recent inquiries and freshly opened accounts; many new accounts in a short span can look risky. Fifth is credit mix, such as a blend of revolving credit and installment loans, which can demonstrate versatility. Negative records like late payments, charge-offs, or collections weigh heavily, while positive actions slowly build momentum. Most scoring models value patterns over flashes of activity, rewarding steady, predictable behavior. Focus on these drivers, and your score will usually follow, even without complex tricks or hacks.
Habits That Build Strong Credit
Sustainable scores come from routine. Start with on-time payments on every account, every month. Automation helps: set autopay for at least the minimum due and calendar reminders for full payments. Keep credit utilization low by charging only what you can comfortably repay and making mid-cycle payments to reduce reported balances. Maintain an emergency fund so an unexpected bill does not lead to missed payments. Avoid applying for multiple accounts at once; spacing applications keeps new credit activity modest. Think long term by keeping older, fee-free accounts open to support the length of credit history. If you are rebuilding, consider a secured card or a credit-builder loan paired with disciplined repayment. Review your statements monthly to catch errors early and track trends. When you need to carry a balance, create a payoff plan that targets the highest interest first while preserving perfect payment history. Consistency compounds; small, repeatable actions shape a resilient credit profile.
Smart Use of Credit Cards
Credit cards are powerful tools when managed intentionally. Monitor your statement closing date and consider paying down balances before it to improve reported utilization; then pay the remainder by the due date to avoid interest. If a single card is nearing a high percentage of its limit, spread purchases or make multiple payments within the cycle. Periodically request a credit limit increase on well-managed accounts, which can lower utilization without new applications. Avoid closing your oldest, no-fee card, as it anchors account age. If a card no longer fits, ask about a product change instead of closing to preserve history. Use cards for planned expenses you would pay anyway, and track spending so rewards never tempt overspending. Becoming an authorized user on a responsibly managed account can help establish history, but choose carefully, as the main user's behavior can affect you. Keep cards active with small, regular transactions to prevent unintended closures.
Repairing and Protecting Your Credit
Strong credit also requires vigilance. Review your credit reports regularly to ensure accounts, balances, and limits are reported accurately. If you find an error, file a dispute with clear documentation; correcting inaccuracies can meaningfully lift your score. If you are behind, contact lenders to ask about hardship options, payment plans, or interest reductions that help you catch up. You may request a goodwill adjustment for a one-time slip on an otherwise clean account, though results vary. Consider a secured card or credit-builder loan to reestablish positive history, and keep utilization modest. For collections, communicate proactively and keep records of any agreements; paying obligations can reduce risk over time. Protect your identity with fraud alerts, a credit freeze when appropriate, strong passwords, and careful sharing of personal information. Prevention matters: monitoring accounts, recognizing phishing attempts, and acting quickly on suspicious activity can save months of repair work and preserve your progress.
A Long-Term Strategy That Lasts
Treat your credit score as part of a broader personal finance plan. Align borrowing with a realistic budget, keep a healthy debt-to-income ratio, and grow an emergency fund so surprises do not trigger missed payments. Time major applications thoughtfully; avoid opening or closing accounts right before seeking a big loan. When comparing lenders for a single purpose, group rate shopping within a short period so inquiries related to the same loan type are often evaluated together. Maintain a sensible credit mix only when it fits your life; never borrow solely for a score. Revisit cards annually to assess fees, benefits, and fit, and adjust through upgrades or product changes rather than frequent new accounts. Track progress with simple metrics: on-time payment streaks, utilization trends, and total balances. Above all, prioritize consistency, patience, and prudence. The real payoff is not just a higher number, but lower borrowing costs and greater financial resilience over time.