The 50/30/20 Rule Explained: Balance Needs, Wants, and Savings
Learn how the 50/30/20 rule helps you split take‑home pay between needs, wants, and savings, with examples, tips, and tweaks for real budgets.
What the 50/30/20 Rule Is
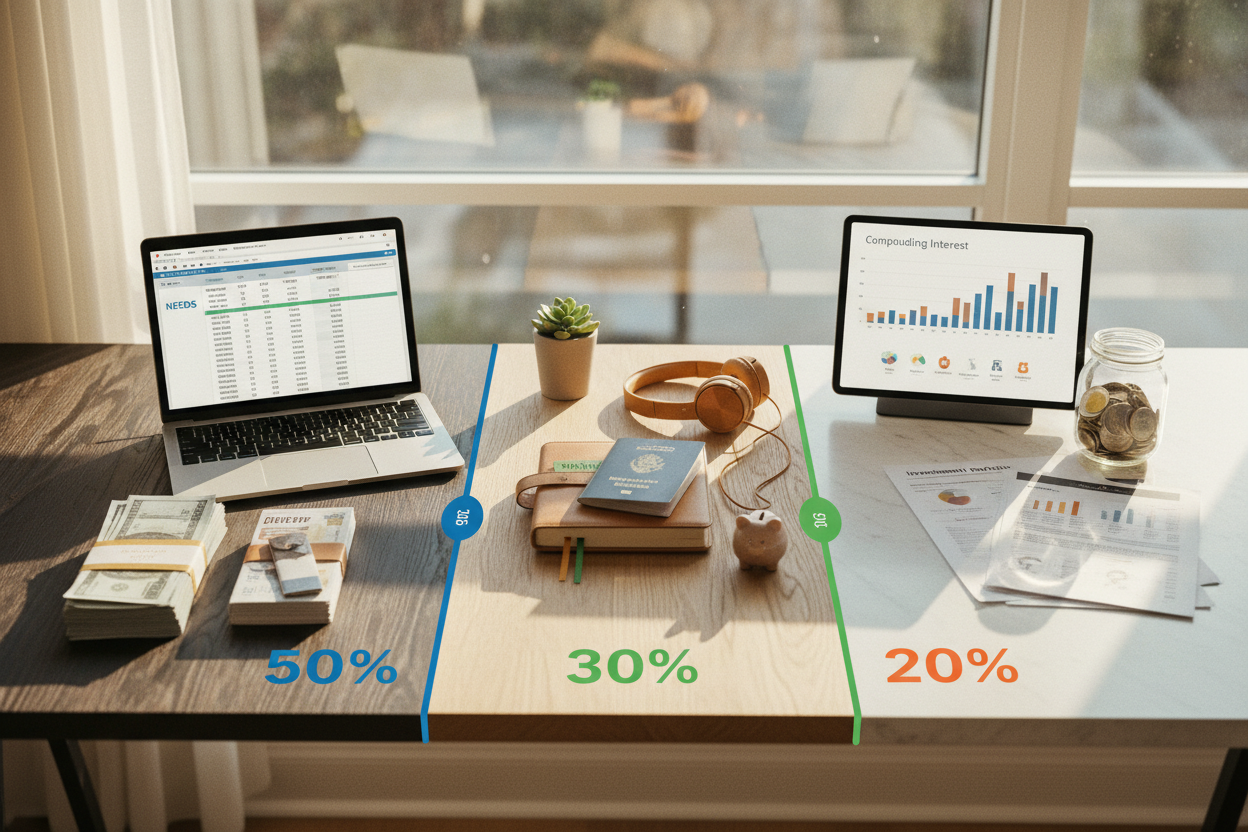
The 50/30/20 rule is a simple, flexible budgeting framework that helps you balance immediate needs with future goals. It divides your after-tax income into three buckets: 50% for Needs, 30% for Wants, and 20% for Savings and debt repayment. Think of it as clear guardrails for your money, not a strict set of handcuffs. By assigning percentages instead of rigid dollar amounts, the rule adapts to pay changes, side income, and evolving priorities. It gives beginners an easy starting point while offering veterans a quick diagnostic to spot imbalances. The focus on after-tax pay keeps things practical, using what actually lands in your account. The payoff is intentionality: you can enjoy life today without sacrificing tomorrow. With a few habits like pay yourself first, category tracking, and periodic check-ins, the 50/30/20 approach creates structure without clutter. It also reduces decision fatigue by turning countless spending choices into three high-level trade-offs you can manage with confidence.
Defining Needs at 50 Percent
Your Needs are essential expenses required to live and work safely. Typical items include housing, basic utilities, staple groceries, transportation to work, minimum debt payments, essential insurance, necessary medical costs, and baseline childcare. A useful test is this: if postponing the expense threatens your health, shelter, or ability to earn, it likely belongs in Needs. Many people accidentally inflate this bucket with convenience or upgrades. Premium data plans, frequent rideshares when public transit or carpooling works, brand-name groceries when generics are fine, or takeout replacing planned meals often sneak in. To right-size Needs, audit recent statements and label each line. Averaging irregular essentials, such as annual premiums or car registration, helps create a realistic monthly figure. To bring this category closer to 50%, negotiate recurring bills, compare insurance, meal plan, reduce waste, and consider housing hacks or commuting alternatives. Guard against lifestyle creep by defining a frugal baseline for groceries and household items, then sticking to it unless income rises sustainably.
Separating Wants at 30 Percent
Your Wants are the meaningful extras that improve comfort, fun, and personal expression. Dining out, streaming services, travel, hobbies, entertainment, fashion upgrades, smart home gadgets, and boutique fitness usually belong here. When in doubt, ask: can I delay this for a month without harming my safety or livelihood? If yes, it is probably a Want. Grey areas exist, like choosing a larger apartment for aesthetics or convenience; the price difference above a safe, livable baseline is typically a Want. Use conscious spending to prioritize high joy-per-dollar purchases while trimming low-value noise. A simple envelope or category system can allocate a set amount each month to guilt-free fun, so you can enjoy experiences fully without anxiety. Conduct a quarterly subscription audit and prune trials, duplicates, or rarely used memberships. Embrace swaps rather than deprivation: a picnic over a pricey brunch, a library hold instead of impulse buys, or free community events that keep social life vibrant while protecting your savings rate.
Saving and Debt at 20 Percent
The Savings and debt bucket is your wealth engine. Aim to build an emergency fund, contribute to long-term retirement savings, create sinking funds for near-term goals, and make extra payments on high-interest debt. A practical order of operations is to secure a basic cash buffer, tackle expensive debt, and steadily grow long-horizon investments. Automate transfers on payday to pay yourself first, treating savings like a nonnegotiable bill. Consider targeted sub-accounts labeled for goals such as travel, car repairs, and home maintenance, so surprises become planned events. For debt, choose a snowball approach (smallest balances first for momentum) or an avalanche approach (highest rates first for efficiency). A quick math example: if your monthly take-home is 3,500, then 1,750 goes to Needs, 1,050 to Wants, and 700 to Savings and debt. Consistency matters more than perfection; even small, automatic contributions compound into meaningful progress while protecting you from setbacks.
Fitting the Rule to Your Situation
Life is not one-size-fits-all, and the 50/30/20 rule recognizes that. In high-cost areas, Needs might temporarily exceed 50%. If so, trim Wants first and commit to gradual improvements, such as negotiating rent at renewal, finding roommates, or reducing transportation costs. With variable or freelance income, use a rolling average to set monthly targets and base your Needs on a conservative minimum. Route any surplus to the Savings bucket to smooth volatility. Families can classify childcare required for work as a Need, while enrichment activities typically land in Wants. Students and early-career earners can still benefit by applying the percentages to modest income, stipends, or allowances; the habit is the win. When big goals loom, like a security deposit or education costs, direct more of the 20% to goal-specific sinking funds. Treat the framework as guardrails, not handcuffs: flexibility keeps momentum alive while preventing the detours that derail long-term financial stability.
Practical Steps to Put It to Work
Start by calculating after-tax income from all steady sources. Next, multiply by 0.50, 0.30, and 0.20 to find your category targets. Map your current spending to Needs, Wants, and Savings using a banking app, spreadsheet, or a simple note with three running totals. Rename categories to match the rule so every transaction must pick a lane. Automate transfers on payday; some employers let you split direct deposit among multiple accounts, which effectively locks in your plan. Add small frictions to Wants, like a 24-hour rule, a wish list, or turning off one-click checkout. Schedule a weekly 10-minute review to reconcile transactions and adjust. Combine the 50/30/20 outline with zero-based planning if you like more detail, but avoid overcomplication that kills consistency. Treat windfalls as accelerants for savings and debt rather than new obligations. Over time, you will internalize the trade-offs and make smarter choices on autopilot.
Adjust, Troubleshoot, and Stay Motivated
Budgeting is a practice, not a performance. If your Needs persistently exceed 50%, fix the math in two stages: first reduce Wants, then pursue structural changes like negotiating pay, adding a side stream, moving closer to work, or downsizing a vehicle. Prevent surprises by building sinking funds for irregular expenses such as car repairs, gifts, or medical copays; these live in the Savings bucket and turn emergencies into line items. Struggling with the 20% target? Start at a smaller percentage and use an automatic escalation each quarter. Make progress visible with trackers or a simple balance snapshot that rewards consistency. Link each dollar to a specific purpose so it feels meaningful, not restrictive. When lapses happen, reset quickly; the next good decision matters more than the last mistake. Keep a short list of priorities, review them monthly, and celebrate wins. Treated as a compass, the 50/30/20 rule keeps you aligned with both stability and enjoyment.